

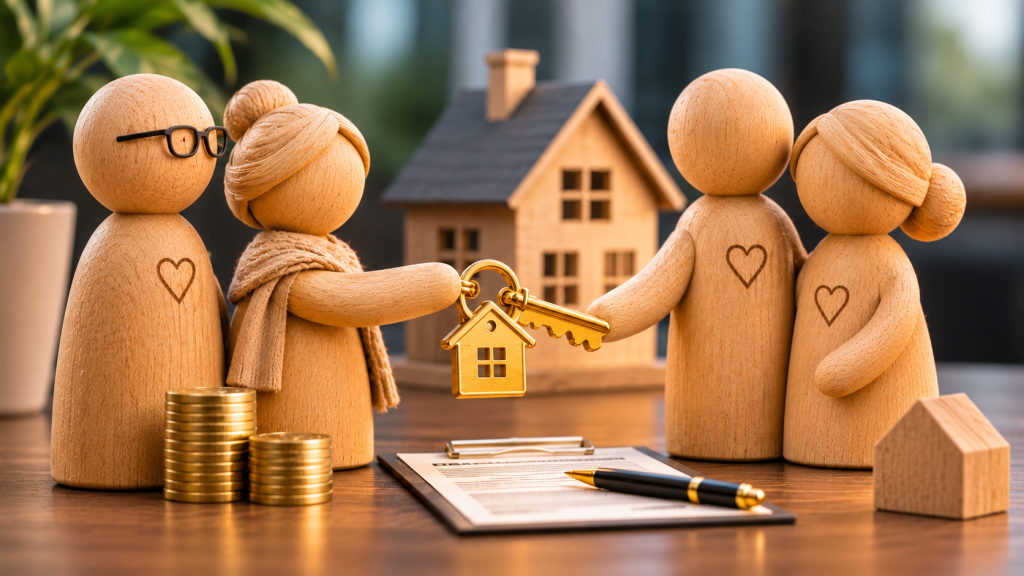
For many first-time buyers, homeownership would simply be out of reach without family support. As property prices continue to outpace wage growth in many parts of the UK, parents and grandparents are increasingly stepping in to help with deposits, mortgage affordability and other costs associated with buying a home.
Often referred to as the “Bank of Mum and Dad”, family financial support has become a significant factor in the housing market. But while discussions often focus on how much money is being given, far less attention is paid to how that support should be structured and protected.
When significant sums are changing hands, taking advice at the outset can help avoid misunderstandings, family disputes and potentially costly consequences later on.
Gift, Loan or Investment?
One of the first questions parents should ask themselves is a simple one:
What exactly is the money intended to be?
Many families treat financial support informally, assuming everyone understands the arrangement. However, problems can arise years later when memories differ or circumstances change.
Parents may intend the contribution to be:
- An outright gift
- A loan to be repaid in the future
- An advance on a future inheritance
- An investment in the property
Each option carries different legal and practical implications.
Where money is intended to be repaid, it is sensible to document the arrangement properly. A simple loan agreement can record the amount advanced, repayment terms and what should happen if the property is sold.
Without documentation, proving what was originally intended can become significantly more difficult.
When Your Child Buys With an Unmarried Partner
One of the most common concerns for parents is providing a substantial deposit only for their child’s relationship to break down in the future.
Many people mistakenly believe that living together creates the same legal rights as marriage. It does not.
The concept of a “common law marriage” is one of the most persistent legal myths in England and Wales.
If your child is purchasing a property with an unmarried partner, careful consideration should be given to how ownership is structured.
Consider a Declaration of Trust
A Declaration of Trust can record:
- How much each person contributed towards the purchase
- Whether family gifts should be protected
- How sale proceeds should be divided
- What happens if further contributions are made later
For example, if parents provide £50,000 towards a deposit and the couple subsequently separate, a properly drafted Declaration of Trust can help ensure that contribution is recognised when the property is sold.
Without one, disputes can be far more difficult and expensive to resolve.
Cohabitation Agreements
Where couples are living together but are not married, a Cohabitation Agreement may also be worth considering.
These agreements can deal with matters such as:
- Ownership of property
- Household bills and expenses
- Savings and investments
- What happens if the relationship ends
Whilst no one enters a relationship expecting it to fail, these agreements often provide clarity and certainty for everyone involved.
Marriage Changes the Picture
Parents are often comfortable helping a child buy a property, but become more cautious when marriage enters the equation.
The concern is understandable. If family money has contributed towards a home or other assets, parents may question how those funds would be treated if the relationship later broke down.
While every family’s circumstances are different, there are practical steps that can help safeguard family wealth.
Prenuptial Agreements
Prenuptial Agreements are becoming increasingly common, particularly where:
- One party enters the marriage with significant assets
- Parents have gifted substantial funds
- Family businesses are involved
- Future inheritances are expected
Although Prenuptial Agreements are not automatically binding in England and Wales, the courts are increasingly likely to uphold them where they have been entered into correctly, with full financial disclosure and independent legal advice for both parties.
For many families, they can provide valuable protection and certainty.
What About Future Inheritances?
Parents and grandparents are often just as concerned about wealth that has not yet been passed down as money being gifted today.
Perhaps there is an expectation that children will inherit property, investments or business interests in the future. Perhaps parents are considering making gifts during their lifetime as part of wider estate planning.
These conversations are rarely easy, but early planning can prevent significant complications later.
Lifetime Gifts
Making gifts during your lifetime may offer inheritance tax planning opportunities, but families should carefully consider:
- The tax implications
- Whether the gift should be documented
- Whether conditions should apply
- How the gift fits within wider family wealth planning
Not every gift needs a complex legal structure, but significant amounts should rarely be transferred without proper consideration.
Trusts and Wealth Protection
In some circumstances, trusts can help protect family wealth across generations.
Trusts may be appropriate where:
- Significant assets are involved
- There are concerns about relationship breakdown
- Beneficiaries are young or vulnerable
- Parents wish to retain some control over how funds are used
Trusts are not suitable for every family, but where long-term wealth protection is a priority, they can provide considerable flexibility and reassurance.
Protecting Relationships, Not Just Money
Conversations about money can feel uncomfortable. Parents want to help their children succeed, not create tension or suggest a lack of trust.
However, putting the right protections in place is not about expecting relationships to fail. It is about ensuring that everyone’s intentions are clearly understood from the outset.
In reality, clear legal arrangements often protect family relationships just as much as family finances.
When expectations are documented and agreed, there is far less scope for misunderstandings, disagreements or disputes in the future.
Planning Ahead
Whether you are helping a child buy their first home, contributing towards a property purchase with a partner, considering a Prenuptial Agreement, or looking at how family wealth will pass between generations, early advice can help ensure your intentions are properly reflected and protected.
The Bank of Mum and Dad has become a vital part of the UK’s property market. But with substantial financial support comes the need for careful planning.
By taking advice before money changes hands, families can help ensure their generosity delivers exactly what was intended: opportunity for the next generation, without creating unnecessary risks for the one that came before.
If you are considering helping a child or grandchild financially, BHP Law’s Residential Property, Family and Private Client teams can advise on the legal arrangements that help protect family wealth today and for future generations.
To start a conversation, contact our team on 0800 590019 or email info@bhplaw.co.uk to arrange a call in the first instance. You can also book a call with a Family Solicitor via our website.